
Digital identity verification has become a critical component of modern financial services. As banks, fintech companies and payment providers move more of their operations online, businesses must be able to verify customer identities accurately, prevent fraud and meet applicable regulatory requirements without creating unnecessary barriers during onboarding.
For customers, the ideal experience is straightforward: they can register, verify their identity and access a service quickly and securely. For businesses, achieving this balance requires the right combination of technology, risk assessment, data protection and carefully designed customer journeys.
Digital identity verification helps bridge this gap, enabling organisations to strengthen security while making digital financial services more accessible.
What Is Digital Identity Verification?
Digital identity verification is the process of confirming that a person is who they claim to be using electronic methods rather than relying exclusively on face-to-face checks or paper-based documentation.
Depending on the service, jurisdiction and associated risk, verification may involve several methods:
- Document verification: Checking passports, national identity cards, driving licences or other accepted identity documents.
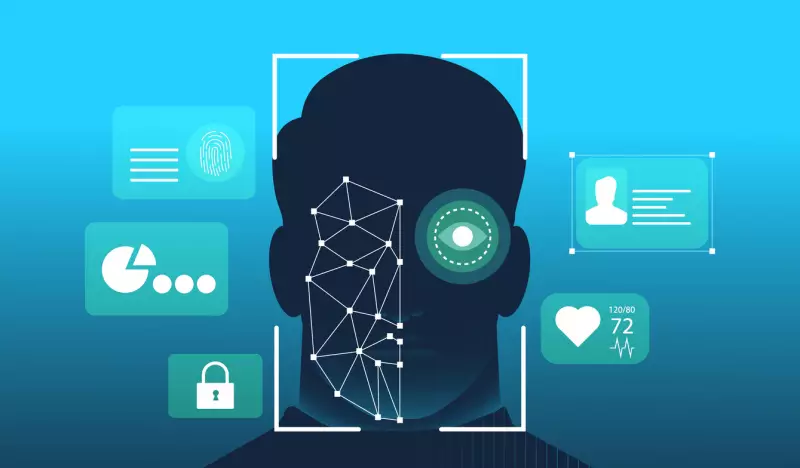
- Biometric verification: Comparing a customer’s facial image with a photograph on an identity document or using other approved biometric methods.
- Liveness detection: Assessing whether a biometric interaction involves a real person rather than a photograph, recording or manipulated image.
- Database and electronic checks: Comparing customer information against reliable data sources.
- Address verification: Confirming a customer’s residential or business address where required.
- Risk-based screening: Conducting relevant sanctions, politically exposed person (PEP) and other compliance checks where applicable.
Not every customer or service requires every method. An effective verification process uses appropriate checks based on the product, customer risk, regulatory obligations and available technology.
Why Digital Identity Verification Matters in Fintech
Digital financial services depend on trust. Businesses need confidence that customers are genuine, accounts are not being opened fraudulently and sensitive information is protected.
Without effective identity verification, organisations may face increased exposure to identity theft, account takeover, synthetic identities, impersonation and other forms of financial crime.
Digital identity verification can help businesses:
- Reduce the risk of fraudulent account creation.
- Support customer due diligence and applicable Know Your Customer (KYC) requirements.
- Strengthen onboarding controls for banking and payment services.
- Improve the consistency of identity checks.
- Reduce dependence on manual document handling.
- Create a clearer audit trail for compliance and risk management.
Verification technology does not eliminate fraud or automatically establish regulatory compliance. Its effectiveness depends on the quality of the checks, the controls surrounding them and how the overall process is managed.
Digital Onboarding: Making the First Interaction Count
Customer onboarding is often the first meaningful interaction between a customer and a financial service provider. A complicated or lengthy process can discourage genuine applicants, while insufficient checks can leave a business exposed to avoidable risks.
Digital onboarding brings registration, document submission, identity checks and relevant compliance procedures into an online journey.
A well-designed process typically aims to:
- Collect only the information needed for the service and applicable requirements.
- Explain clearly why identity information is required.
- Guide customers through document capture and verification.
- Provide understandable instructions if an image is unclear or a check cannot be completed.
- Route higher-risk or inconclusive cases for additional review where appropriate.
- Communicate the outcome and explain any next steps.
Automation can reduce unnecessary delays, but it should not make the process confusing or leave legitimate customers without a way to resolve verification problems.
The objective is not simply to make onboarding faster. It is to make it efficient, understandable and proportionate to the risk.
Biometrics and the Role of Facial Verification
Biometric technology is increasingly used to support digital identity verification, particularly when customers open accounts remotely.
Facial verification can compare a live or newly captured image with a photograph on an identity document or another authorised reference. Combined with document authenticity checks and liveness detection, it can help identify certain forms of impersonation.
However, biometrics must be implemented carefully.
Businesses should consider:
- Accuracy: How reliably the system performs under different lighting conditions, camera quality and customer circumstances.
- Presentation attacks: Whether the technology can detect attempts to use photographs, videos, masks or other forms of impersonation.
- Accessibility: Whether customers who cannot complete a particular biometric check have an appropriate alternative.
- Privacy: How biometric information is collected, processed, secured and retained.
- Human review: How customers can challenge an incorrect result or request assistance.
Biometric systems can produce false rejections and may perform differently across demographic groups or operating conditions. Organisations should evaluate performance, monitor outcomes and provide suitable escalation routes.
Biometric information can also receive special protection under applicable data protection laws. Businesses should establish an appropriate legal basis and safeguards before introducing these technologies.
Artificial Intelligence in Identity Verification
Artificial intelligence can strengthen identity verification by helping analyse documents, detect anomalies and identify patterns associated with potential fraud.
Depending on the system, AI-assisted verification may support:
Document analysis: Identifying inconsistencies, signs of manipulation or information that does not match expected document characteristics.
Fraud detection: Highlighting suspicious application patterns, repeated attempts or information associated with potential identity misuse.
Risk assessment: Helping determine when additional checks or manual investigation may be appropriate.
Process automation: Reducing repetitive manual work and directing straightforward cases through a more efficient verification journey.
AI should support, rather than replace, appropriate governance and accountability. Businesses need to understand the limitations of their systems, assess the quality of automated decisions and ensure that significant decisions can be reviewed where necessary.
Clear procedures are particularly important when verification results affect a customer’s ability to access a financial service.
Balancing Security with a Frictionless Customer Experience
One of the biggest challenges in digital identity verification is finding the right balance between robust controls and ease of use.
Excessive friction can cause customers to abandon applications, repeat steps or seek assistance. Weak controls, on the other hand, can increase exposure to fraud and compliance failures.
A more effective approach combines risk-based verification with customer-centred design.
Use proportionate verification
Apply checks that reflect the nature of the service, relevant legal requirements and the assessed level of risk. Avoid collecting additional information without a clear purpose.
Reduce unnecessary repetition
Where legally permitted and technically appropriate, use secure integrations and reusable verified information to avoid asking customers to submit the same details repeatedly.
Explain what customers need to do
Simple instructions, clear document requirements and transparent explanations can reduce errors and make the process feel more trustworthy.
Provide alternative verification routes
Customers may have older devices, accessibility needs or identity documents that the automated process cannot read. Appropriate alternative methods and support can help prevent legitimate applicants from being excluded.
Design effective exception handling
When a check fails, the system should distinguish between an actual risk signal and a technical problem, such as poor image quality. Clear next steps can reduce frustration without weakening security controls.
Monitor completion and failure rates
Businesses should measure application completion, verification failures, abandonment and the time required to resolve exceptions. These indicators can help identify unnecessary friction while maintaining appropriate risk controls.
Identity Verification and Regulatory Responsibilities
Digital identity verification is closely connected to KYC, customer due diligence and anti-money laundering (AML) controls. However, the specific requirements depend on the jurisdiction, type of institution, financial product and applicable regulatory framework.
Businesses may need to verify customer identity, understand the purpose of a business relationship, assess risk, screen against relevant lists, maintain records and conduct ongoing monitoring.
For regulated financial services, outsourcing verification technology does not necessarily transfer the regulated firm’s responsibility for its compliance obligations.
Before adopting an identity verification provider, organisations should assess:
- The provider’s verification methods and evidence sources.
- Coverage across relevant countries and identity documents.
- Data processing, privacy and information security arrangements.
- Auditability, reporting and record retention.
- Procedures for failed checks, escalations and suspicious activity.
- Service availability, resilience and incident response.
- Contractual responsibilities and oversight arrangements.
A technology provider can support the verification process, but businesses must ensure that the overall framework satisfies their own legal and regulatory obligations.
Data Protection and Customer Trust
Identity verification involves sensitive personal information, including identity documents and, in some cases, biometric data. Customers need confidence that their information will be handled responsibly.
Businesses should apply data protection principles throughout the verification lifecycle.
This includes collecting only necessary information, restricting access, protecting data in transit and at rest, defining appropriate retention periods and securely disposing of information when it is no longer required.
Organisations should also understand where information is processed, which third parties can access it and whether international data transfers require additional safeguards.
Privacy notices should explain the purpose of verification in language customers can understand. Security measures should be supported by clear governance, documented procedures and appropriate monitoring.
Strong data protection is not merely a technical requirement. It is an important part of establishing customer confidence in digital financial services.
Integrating Identity Verification into Financial Platforms
Identity verification is most effective when it forms part of a broader digital financial infrastructure rather than operating as a disconnected step.
For banks, payment providers and fintech platforms, integration may involve connecting verification services to customer onboarding, payment systems, account management, fraud monitoring and compliance workflows.
A well-planned integration should consider:
- API connectivity: Reliable communication between the verification provider and the wider platform.
- Workflow orchestration: Ensuring that identity checks occur at the appropriate stages of onboarding.
- Data consistency: Avoiding unnecessary duplication and mismatched customer records.
- Security controls: Using appropriate authentication, access restrictions and secure data transmission.
- Operational visibility: Providing teams with clear status information and records of verification outcomes.
- Scalability: Supporting increased application volumes without compromising performance.
- Ongoing monitoring: Reassessing customer information when required by the applicable risk framework.
Businesses should also test integrations for failure scenarios. A verification provider becoming temporarily unavailable, for example, should not result in uncontrolled approvals or leave customers without clear instructions.
Measuring the Effectiveness of Identity Verification
An effective verification programme should be evaluated against both security and customer experience.
Useful performance indicators may include:
- Identity verification completion rate.
- Average time required to complete verification.
- Application abandonment rate.
- False rejection and manual review rates.
- Confirmed identity fraud incidents.
- Cost per successfully verified customer.
- Customer support requests relating to onboarding.
- System availability and verification service response times.
These measures should be assessed together. A high approval rate is not necessarily a sign of success if fraud controls are inadequate, just as a low fraud rate may conceal a process that incorrectly rejects too many legitimate customers.
Regular reviews help organisations improve verification methods, identify operational weaknesses and maintain an appropriate balance between risk and accessibility.
The Future of Digital Identity Verification
Digital identity verification is likely to become more integrated, automated and responsive to changing customer and regulatory needs.
Developments in AI-assisted document analysis, privacy-enhancing technologies, digital identity credentials and interoperable identity systems may help streamline verification while improving control over personal information.
Reusable digital credentials could reduce repeated document submission in suitable environments, while more sophisticated fraud detection may help identify increasingly complex attempts at impersonation.
Nevertheless, technology alone will not resolve every challenge. Organisations will still need to address privacy, accessibility, bias, cybersecurity, accountability and differences between regulatory jurisdictions.
The strongest solutions will combine modern verification technology with transparent processes, effective governance and a clear focus on customer trust.
How Akyol Fintech Views Digital Identity Verification
At Akyol Fintech, digital identity verification is an important consideration in the development of secure, accessible and customer-focused financial services.
For fintech businesses, payment providers and digital banking platforms, the challenge is to bring together identity checks, onboarding workflows, security controls and compliance processes in a way that supports both operational efficiency and a positive customer experience.
By considering identity verification as part of the wider financial technology architecture, businesses can develop more consistent digital journeys while maintaining appropriate safeguards for customers, data and financial operations.
Whether a business is developing a digital banking proposition, integrating payment services or modernising its onboarding processes, the right technology strategy begins with understanding its customers, operational requirements and regulatory responsibilities.
Explore how Akyol Fintech can support your financial technology objectives.
Visit Akyol Fintech or contact our team to discuss your requirements.
Disclaimer
This article is provided for general informational purposes only and does not constitute legal, regulatory, financial or cybersecurity advice. Digital identity verification requirements vary by jurisdiction and business activity. Organisations should obtain appropriate professional advice and assess their own regulatory, privacy and security obligations before implementing verification solutions.